Mastercard on why AI-powered commerce needs a new layer of trust
Mastercard’s Mark Elliott says agentic commerce will only scale if people can delegate a purchase without giving up control.


An AI agent can already help someone find a product, compare prices, and narrow down the choices. The harder moment comes when it is time to pay.
Once an agent can complete a transaction, commerce is no longer a simple interaction between a shopper and a checkout page. A consumer has to decide what the agent is allowed to do, how much it can spend, which merchants it can use, and when it needs to ask for approval.
That is the trust challenge at the center of agentic commerce.
Checkout.com’s 2026 MENA Digital Commerce report found that 50% of consumers in the region are comfortable letting an AI agent shop on their behalf. At the same time, 55% cited privacy as a barrier to adoption.
The gap matters. People may be open to AI assistance, but they are not ready to hand over control without a clear understanding of what happens next.
For Mark Elliott, Division President for East Arabia at Mastercard, the shift is not about choosing convenience over security. Convenience works only when the customer knows the system is operating within the limits they set.
“We are moving from direct human transactions to delegated trust,” he says.
A PURCHASE IS NOW A SET OF PERMISSIONS
Traditional e-commerce is built around an immediate decision: a customer selects an item, enters their details, and authorizes a payment.
Agentic commerce changes that sequence. The customer may authorize an agent to research products, make comparisons, or handle repeat purchases. But each permission needs a boundary.
Can the agent buy from any merchant, or only approved ones? Can it complete a purchase up to a certain value? Can it act only for a set period? And what happens when it encounters a purchase that falls outside the customer’s instructions?
“The critical question becomes: did the agent act within the user’s intended scope?” Elliott says.
Mastercard’s answer is Agent Pay, which the company says is designed to use tokenization and authenticated credentials to let AI agents transact within consumer-defined rules. Rather than exposing a customer’s underlying payment details, the system is intended to give the agent a restricted credential linked to a specific task, limit, or duration.
That distinction is important. An AI agent should not receive a blanket right to spend. It should be granted permission to perform a defined job.
For Mastercard, this builds on decades of helping money move safely and seamlessly around the world through trusted infrastructure. As commerce evolves, it’s extending the same principles of security, interoperability and consumer protection to a world in which AI agents increasingly initiate transactions.
As part of these efforts, the company is developing a framework it calls Verifiable Intent. The idea is to create a tamper-resistant record of what a customer authorized, what the agent was permitted to do, and how the transaction was completed.
For consumers, that should make an automated purchase easier to question or dispute. For merchants and banks, it creates a clearer trail when something goes wrong.
Establishing a verifiable record of consumer authorization will also be important in determining accountability, helping issuers, merchants and payment networks assess disputes and establish whether an agent acted within the permissions granted. As agentic commerce evolves, clear liability frameworks and dispute resolution processes will be essential to protecting consumers and maintaining trust.
THE RIGHT KIND OF FRICTION
The ambition for digital commerce has long been to make payments increasingly seamless and ultimately invisible. Agentic commerce does not change that ambition, but it introduces a new consideration: when should a transaction proceed without interruption, and when should the consumer be brought back into the decision?
For Elliott, the answer lies in applying “friction” intelligently. When an AI agent operates within clearly established permissions, the transaction should be able to proceed seamlessly. Additional verification or approval should be reserved for exceptions, such as a purchase that exceeds a spending limit, falls outside the consumer’s instructions, or triggers a potential security concern.
The point is not to force people through another checkout process. It is to make control visible at the moment it matters.
A well-designed approval screen, spending limit, or notification can give a customer confidence without making the technology feel burdensome. Poorly designed security, by contrast, encourages people to bypass the safeguards altogether.
“The goal is to make security and control feel like an intuitive and empowering part of the experience, not a burden,” Elliott says.
TRUST HAS BECOME A COMMERCIAL QUESTION
For merchants, this is not simply a compliance issue.
If consumers do not trust an agent to act on their behalf, they will use it for research but stop short of letting it buy. That could make AI useful for discovery while limiting its value at the point of transaction.
Research from Gartner in 2026 illustrates the hesitation among US consumers. While shoppers expressed interest in AI shopping assistance, only 11% said they were willing to let an agent make a purchase decision in lower-stakes categories such as household supplies and personal care.
That means trust has to show up in commercial results: completion rates, repeat use, dispute volumes, fraud losses, and customer loyalty.
For Elliott, businesses that treat trust as a legal checkbox will miss the point. In agentic commerce, trust is part of the product.
It is also likely to determine which brands customers allow into more consequential decisions. An agent may be able to choose a repeat grocery order today. The larger test is whether people will let it book travel, change an insurance policy, or make a high-value purchase tomorrow.
A REGIONAL TEST CASE
The Middle East’s high level of digital payment adoption makes it a promising market for this next phase of commerce. The UAE is already emerging as an early testing ground for agentic commerce.
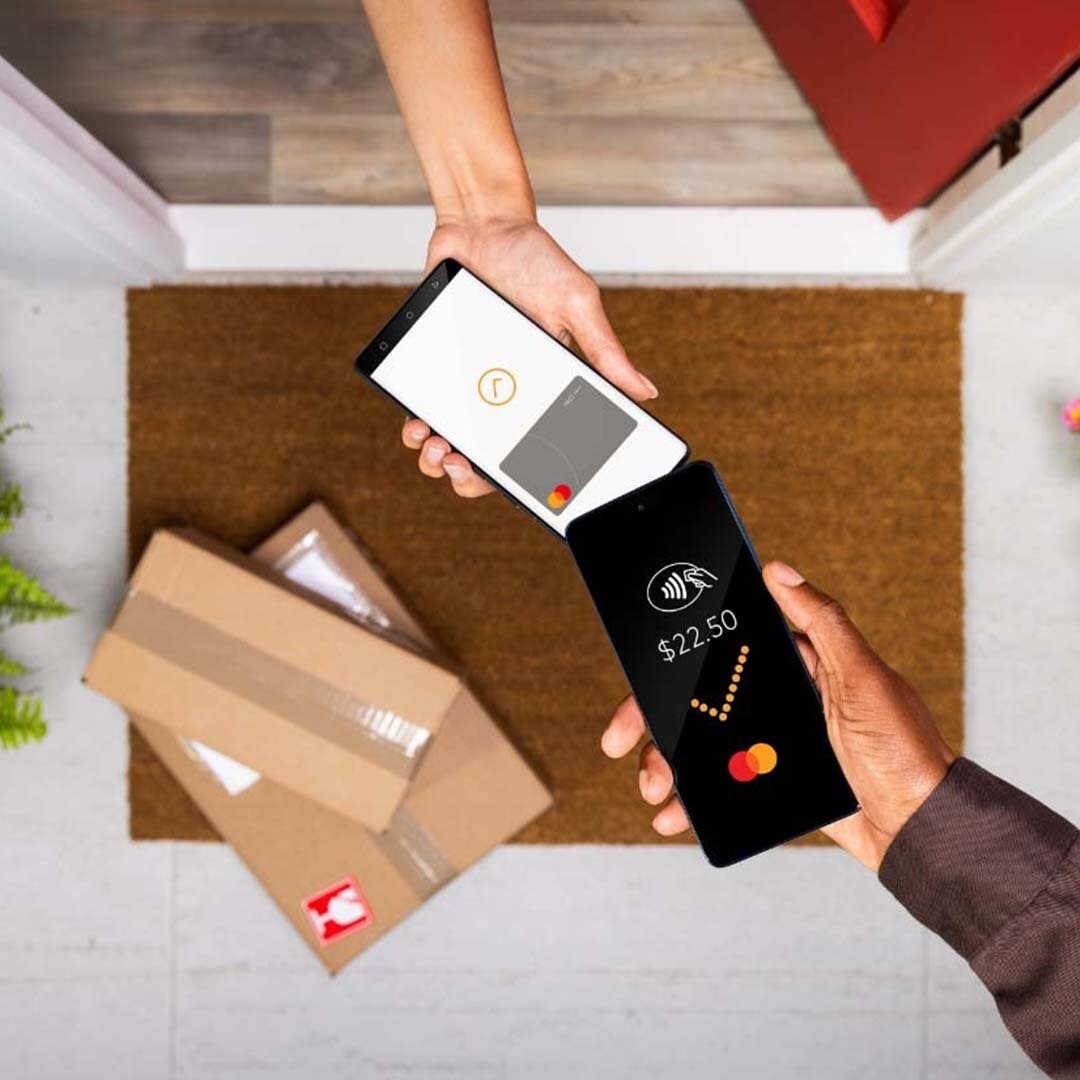
In collaboration with Majid Al Futtaim, Mastercard demonstrated its first Agent Pay transaction outside the United States, illustrating how AI agents can move beyond product discovery to completing purchases through secure, authenticated payment experiences.
While broader consumer adoption is still in its early stages, the demonstration represents an important step toward translating agentic commerce from concept to practical application.
But adoption will depend less on whether consumers understand AI and more on whether they believe it is working in their interest.
Elliott sees demand shifting beyond transaction security alone. Consumers increasingly want to know what data is being used, why it is being collected, and how they can change their permissions.
That puts the focus on identity, cybersecurity, and data protection as much as on payments.
Consumers also expect security to be proactive rather than only taking effect after fraud has occurred. Mastercard has invested over $12 billion globally in cyber innovation and the use of AI for fraud detection, reflecting a broader move toward identifying and preventing threats before they impact customers.
A trusted transaction must establish that the customer is genuine, the agent has valid authority, and the merchant or service provider is legitimate. It will also need to preserve a record of who approved what.
Mastercard is building its regional work through its Center for Advanced AI and Cyber Technology in Dubai, launched in collaboration with the UAE’s Artificial Intelligence, Digital Economy and Remote Work Applications Office, and Mastercard Lighthouse UAE, which supports AI and fintech startups. These initiatives contribute to an ecosystem in which emerging technologies can be developed, tested and applied to real-world challenges.
These efforts support the company’s broader ambition to provide the foundation for commerce, trust and participation as technology evolves, helping more people and businesses realize their potential.
The businesses that succeed in agentic commerce will not be those that remove the most clicks. They will be the ones who make delegation feel safe, understandable, and reversible.
That is the real standard for AI-powered shopping: not whether an agent can buy, but whether a customer still feels in control after it does.
Featured Videos
Today's Top Stories:
More Top Stories:
FROM OUR PARTNERS