- | 9:00 am
How Saudi Arabia’s project pivot is building an entire supplier economy
The next phase of Vision 2030 is creating a broader opportunity for suppliers, service providers and specialist operators
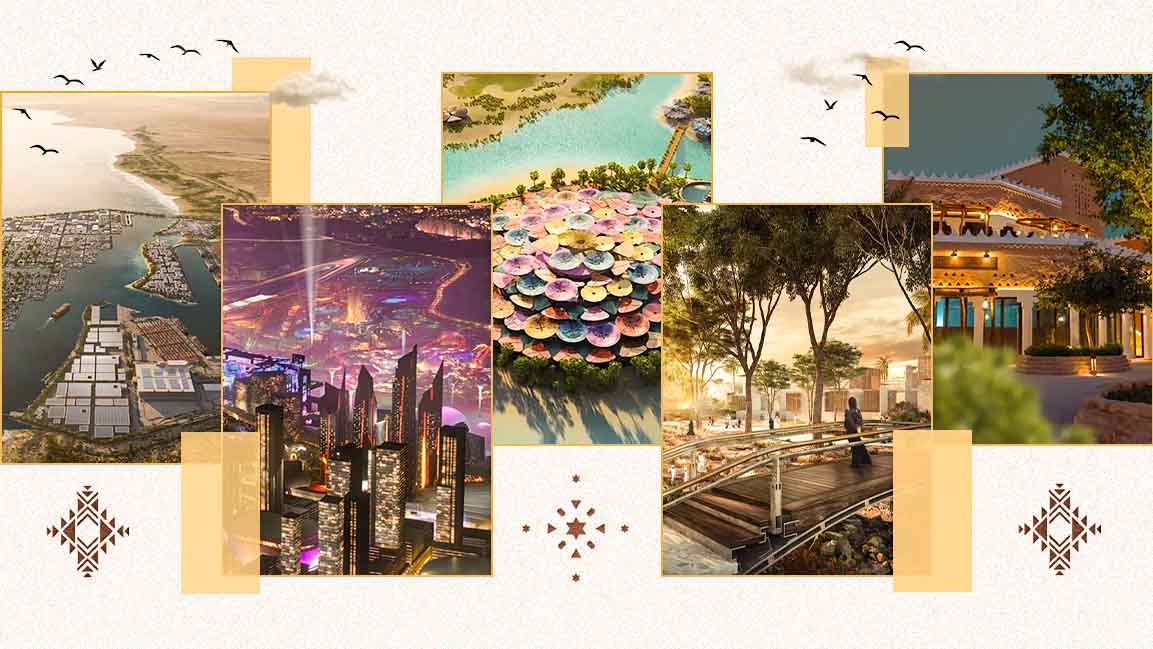


Saudi Arabia’s Vision 2030 has entered a stage that may not be as flashy, but is even more crucial. Now, as major projects begin, the real economic activity is happening among companies that supply materials, handle fit-outs, provide industrial goods, offer worker housing, run catering services, and manage facilities across the country’s construction efforts. For local and foreign businesses, joining this ecosystem is now an easier and potentially more sustainable way to enter the Saudi market than competing for the biggest contracts.
BEYOND THE GIGA PROJECTS
The focus is shifting from large-scale site preparation to finishing projects and handing them over, says Morshed Aldossary, Procurement Supervisor at Rawabi Vallianz Offshore Services Projects, as projects with strict deadlines, like Expo 2030, sports venues, and industrial expansions, are progressing quickly.
This urgency is “driving huge demand for fit-out, MEP, fire safety, and facilities management.” At the same time, the region’s mega developments are being divided into practical, phased packages to help manage cash flow and supply chains more efficiently.
Describing the trend in broader terms, Amar Hussain, Associate Partner for Research in the Middle East at Knight Frank Middle East, says the market is moving “increasingly from planning and development towards execution, delivery and operation.” This change, he adds, is “broadening demand for fit-out, logistics, facilities management, maintenance and other operational services.”
FASTEST-GROWING SUPPLIER CATEGORIES
Hussain explains that supplier demand changes as a project moves forward. Fit-out and construction suppliers benefit most when projects are almost finished, while facilities management and maintenance firms become important once the assets are up and running. This shift at each stage is changing who gets contracts and has pushed suppliers to adapt quickly.
Most suppliers today are mid-sized, flexible local companies or joint ventures. Many have had to double their capacity and staff in less than 18 months to keep up with demand, says Aldossary. He believes these firms succeed by focusing on “cash flow discipline, good internal systems, and keeping inventory local rather than waiting on import lead times.”
This pressure to grow matches where demand is highest. Aldossary highlights fit-out and operations and maintenance as the fastest-growing areas, each for different reasons. Commercial spaces and hotels need fit-out work as they prepare to open, while finished sites need ongoing maintenance, spare parts, and safety support to keep running. Hussain also sees supplier demand as a function of a project’s progress from delivery to operation.
Both experts agree that these categories are closely connected. Aldossary says they are fully linked. For example, a 5,000-person worker camp is more than just a construction job. It “instantly creates demand for modular panels, long-term catering, power generation, waste management, and safety systems.” He explains that one contract often leads to several others.
While construction work can create demand for accommodation, transport, and catering, finished assets need ongoing maintenance and facilities management.
A WAY IN FOR FOREIGN FIRMS
Hussain believes that offering specialist services and expertise could be a practical way for foreign companies to enter the Saudi market. However, he points out that localization, regulations, and local partnerships remain important. As the development cycle progresses, he expects demand for early-stage construction work to slow in some areas, while services such as operations and asset management will become more important.
Talking about how to enter the market, Aldossary says bidding for major contracts involves “massive balance sheet risk and high competition,” but joining as a specialized supplier or joint-venture partner helps foreign firms connect with local networks, navigate regulations more easily, and build steady cash flow.
He notes that demand is dropping for basic earth-moving equipment and general civil work as early site preparation finishes. On the other hand, workforce housing and camp management are growing rapidly, with higher-quality, ESG, and safety standards pushing out informal operators in favor of more organized companies.
PLANNING TO PERMANENCE
Hussain describes this phase as a shift from announcements and planning to a focus on execution, delivery, and operation. This change is opening up more opportunities throughout the supply chain. When asked if the supplier economy will last, he says that the increasing number of completed real estate projects will require ongoing management, maintenance, and services, which will keep demand strong even after individual development projects are completed.
Aldossary makes a clear distinction between the two phases. He explains that phase one focused on master planning, large-scale allocations, and the start of construction. Phase two, however, is about execution, building local content, and preparing for operations, with the focus shifting to private-sector action.
He is also clear about the future of the supplier economy. While giga projects started this trend, he says the supply chain now forming in local manufacturing, specialized maintenance, and logistics is not tied to any single project. Once these businesses are established, they will be able to serve industrial cities, general commercial activities, and markets across the GCC.